How Nigerians can access Tinubu’s ₦100m morgage loan
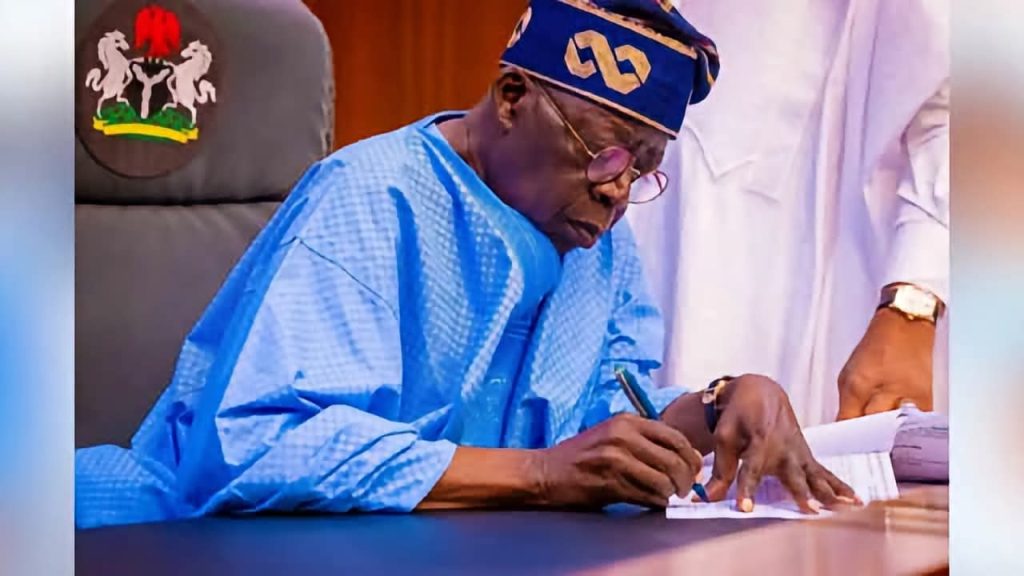
With the Federal Government offering eligible Nigerians access to mortgages of up to ₦100 million at a fixed interest rate of 9.75 per cent, many Nigerians struggling with rising house rents may be wondering how to benefit from the programme.
President Bola Tinubu announced the facility on November 17, explaining that the initiative was designed to expand access to long-term housing finance and make homeownership more attainable for working Nigerians.
The facility operates through the ₦1 trillion Ministry of Finance Incorporated Real Estate Investment Fund (MREIF), which provides long-term funding through participating banks and mortgage institutions.
Under the programme, qualified applicants can access mortgages of up to ₦100 million, repayable over a period of up to 20 years, at a fixed annual interest rate of 9.75 per cent.
The announced minimum initial equity contribution is 10 per cent of the property’s value.
Tinubu said more than 2,300 Nigerians across 27 states had already accessed ₦160 billion in mortgage financing through MREIF.
But how can an interested Nigerian apply, what are the requirements, and what should prospective homeowners know before submitting an application?
Who is eligible to apply for Tinubu’s morgage?
According to MREIF’s published homebuyer eligibility criteria, applicants must be Nigerian citizens and satisfy the programme’s income and credit requirements.
The applicant must also demonstrate the financial capacity to repay the mortgage over the agreed period.
However, there is no single minimum monthly salary stated on MREIF’s general homebuyer eligibility page. Participating financial institutions assess applicants based on their income, existing financial obligations, credit history and repayment capacity.
Individual banks may also impose additional requirements.
For instance, Stanbic IBTC’s published MREIF mortgage conditions require applicants to be at least 21 years old, with the mortgage expected to mature before they turn 60 or reach their applicable retirement age.
The bank also requires salaried applicants to have at least six months of employment with their current employer and confirmed permanent employment status. Business owners must demonstrate verifiable cash flow.
How to apply for the mortgage
Interested Nigerians can begin their applications through the official MREIF website at [www.mreif.com.ng](https://www.mreif.com.ng/) or its dedicated housing portal at [housing.mreif.com.ng/pre-qualifier](https://housing.mreif.com.ng/pre-qualifier).
The application process involves the following steps:
1. Visit the MREIF portal
Applicants should visit the official website and access the homebuyer section to begin the process.
They can also use the pre-qualification facility to provide information about their age, employment status, monthly income, proposed deposit and preferred repayment period.
2. Check your borrowing capacity
The pre-qualification process helps applicants estimate how much they may be able to borrow based on their income, age and available equity contribution.
This is important because although the programme provides mortgages of up to ₦100 million, not every applicant will automatically qualify for the maximum amount.
Pre-qualification does not constitute final approval. The participating financial institution must still assess the applicant’s financial position and supporting documents.
3. Identify a suitable residential property
Applicants must identify a property they intend to purchase and obtain the relevant sales or provisional offer letter.
MREIF provides access to residential property listings and inspection arrangements through its platform.
The property must satisfy the lender’s requirements, particularly regarding its ownership documents and legal title.
The programme is intended to finance residential home purchases, not provide unrestricted cash for personal spending or the purchase of undeveloped land.
4. Prepare and upload the required documents
Applicants must submit personal, employment, financial and property-related documents for assessment.
5. Complete the application through a participating financial institution
Following the initial application, the mortgage will undergo further assessment by the participating bank or mortgage institution.
The institution will examine the applicant’s income, creditworthiness, repayment capacity and the property’s documentation before communicating its decision and mortgage terms.
Successful applicants will then complete the required equity contribution, legal documentation and insurance arrangements before disbursement.
Documents required for the application
The MREIF website and its downloadable mortgage application requirements provide documentation guidelines for employed and self-employed applicants.
For salaried applicants, the requirements include:
– Completed mortgage application form and loan application letter.
– Bank Verification Number (BVN) printout.
– Valid means of identification and passport photograph.
– Recent electricity or utility bill.
– Employment or appointment letter, confirmation letter or last promotion letter.
– Staff identity card and curriculum vitae.
– Salary account statements and recent payslips.
– Tax Identification Number (TIN) or tax clearance documentation.
– Signed property sales or provisional offer letter.
– Retirement Savings Account statement, where applicable.
The downloadable application checklist also identifies additional requirements, including a letter of introduction from the applicant’s human resources department, two reference forms, evidence of equity contribution and a preferred Primary Mortgage Bank account opening form.
For self-employed applicants, the requirements are more extensive because the lender must establish the applicant’s business activities and financial capacity.
These include:
– Completed mortgage application form and loan application letter.
– BVN and valid means of identification.
– Three years’ personal bank account statements.
– Three years’ company bank account statements.
– Corporate Affairs Commission (CAC) registration documents.
– Company profile, including a list of clients.
– Tax certificate or TIN.
– Evidence of trade association membership payments and endorsement.
– Curriculum vitae and relevant business records.
– Signed property sales or provisional offer letter.
Additional documents, including audited or management accounts, evidence of running contracts and contract renewals, may also be required.
Applicants should note that MREIF’s online homebuyer page lists six months of recent payslips for employed applicants, while its downloadable application checklist requests one year of payslips and salary account statements. Prospective borrowers should therefore confirm the current document checklist with their chosen lender before submitting their applications.
How much deposit must applicants pay?
Under the terms announced by President Tinubu, applicants are expected to make an initial equity contribution of at least 10 per cent of the property’s value.
For example, a Nigerian seeking to purchase a house worth ₦10 million would be required to provide an initial contribution of ₦1 million, while the remaining ₦9 million would be financed through the mortgage.
Using this example, Tinubu said the beneficiary would repay approximately ₦85,400 monthly over 20 years at the announced interest rate.
The 10 per cent contribution is particularly important because it reduces the amount prospective homeowners must raise before accessing mortgage financing.
However, applicants should confirm the exact equity requirement with their selected lender. An older entry on MREIF’s online FAQ still refers to a 20 per cent contribution, although its current homebuyer page and the President’s latest announcement state 10 per cent.
Can pension contributions help with the initial deposit?
Yes. Tinubu also disclosed that eligible contributors under Nigeria’s Contributory Pension Scheme may access up to 25 per cent of their Retirement Savings Account (RSA) balance towards their initial mortgage deposit.
This means qualified pension contributors may be able to use part of their accumulated retirement savings to meet the equity contribution requirement.
However, access to the funds is subject to applicable pension regulations and approval through the relevant Pension Fund Administrator.
Applicants interested in this option should contact their pension administrators to establish their eligibility and the documentation required.
Can married couples apply together?
Married applicants can submit joint mortgage applications with their spouses to improve their borrowing capacity.
Combining the financial strength of both applicants may make it easier to satisfy the lender’s income and repayment requirements.
However, joint applications remain subject to the participating institution’s conditions, including the documentation required from both applicants.
Which banks are participating?
MREIF works with commercial banks and mortgage institutions to provide financing to qualified homebuyers.
Institutions currently displayed on its website include Access Bank, FCMB, Fidelity Bank, Stanbic IBTC Bank, Infinity Trust Mortgage Bank and Homebase Mortgage Bank, among others.
Prospective applicants are advised to confirm directly with their preferred institution that it is processing applications under the relevant MREIF mortgage product and to obtain its specific requirements before proceeding.
What applicants should know before accepting the mortgage
Although the facility offers a fixed interest rate of 9.75 per cent and a repayment period of up to 20 years, applicants should understand that it is a mortgage loan and not a government housing grant.
Beneficiaries are required to repay the borrowed amount with applicable interest and other charges over the agreed period.
The published MREIF platform terms also provide for a one per cent platform success fee payable by homebuyers. Applicants should request a written breakdown of all applicable platform, banking, legal, valuation, insurance and property registration charges before committing to the transaction.
They should also independently verify the property’s ownership and title documents, preferably with the assistance of a qualified property lawyer, before making payments or signing final agreements.
Applicants are equally advised to use only the official MREIF platform and recognised participating financial institutions, and to avoid individuals promising guaranteed mortgage approval in exchange for unofficial payments.
The programme is expected to provide more Nigerians with access to long-term housing finance, particularly those who have struggled to raise the full purchase price of residential properties while meeting rising rental obligations.